📉 The One Thing That Matters Today
Inflation has changed the rebound's test. After October consumer prices rose faster than expected, US stocks turned lower and the 10-year Treasury yield returned to 5.01%. Can corporate borrowing costs remain contained as rates rise?
- S&P 500 🔻0.8%; Nasdaq 100 🔻1.2% in the November 10 afternoon snapshot: growth is taking the bigger hit.
- December Fed contract 🔺95% for a hike: 84% prices a quarter point and 11% at least half a point, versus 4% for no change. Traded probabilities, not a Fed forecast.
Hy Spread
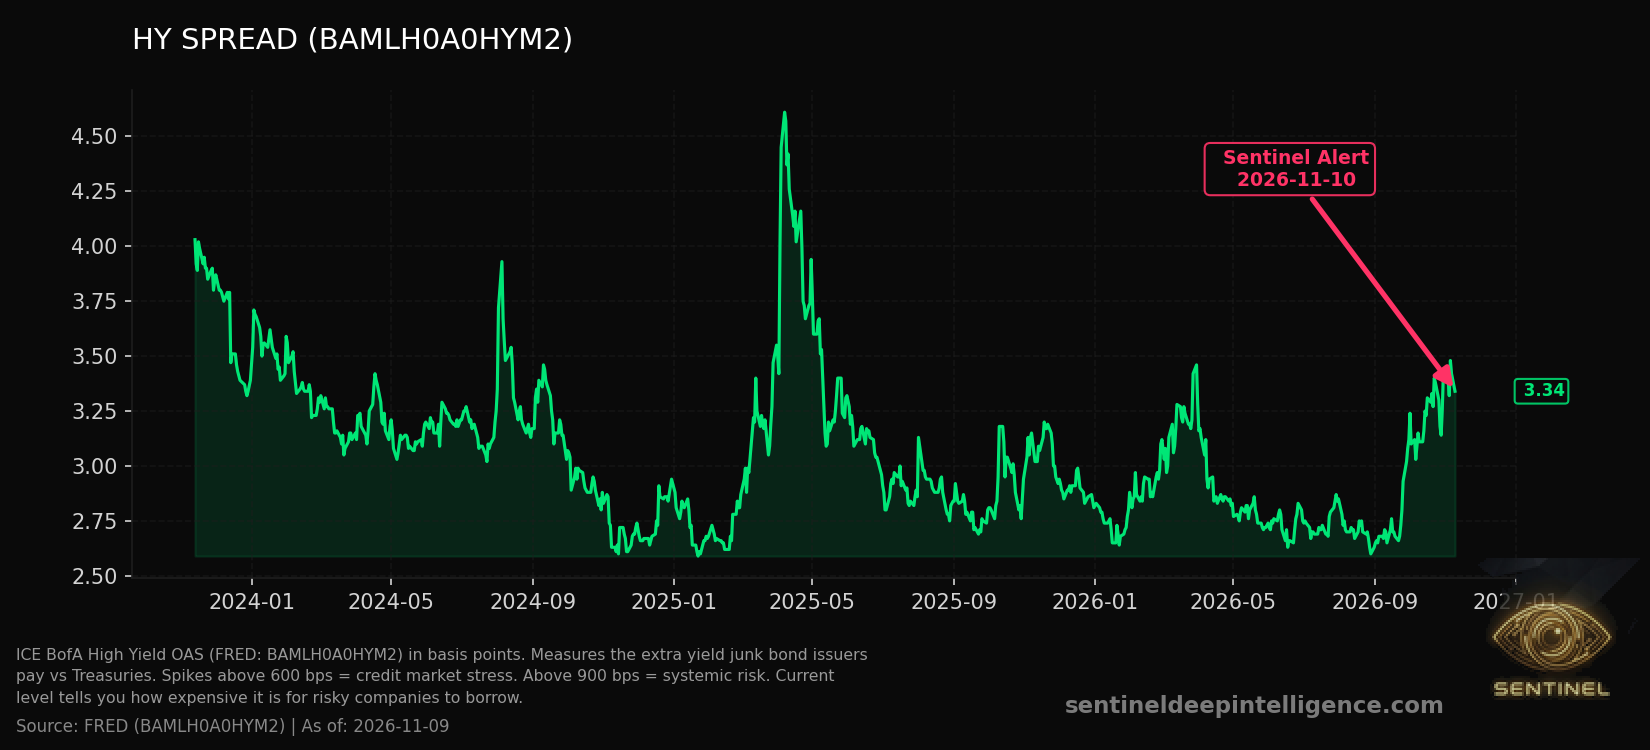
ICE BofA High Yield OAS (FRED: BAMLH0A0HYM2) in basis points. Measures the extra yield junk bond issuers pay vs Treasuries. Spikes above 600 bps = credit market stress. Above 900 bps = systemic risk. Current level…
🔎 Active Lens: The Borrowing-Cost Test
SIGNAL: Stocks reflect the rate shock; credit has not confirmed it. Dealer hedging cushions stock swings, not corporate refinancing costs.
- FACT: The latest dated high-yield spread, the extra interest weaker borrowers pay over Treasuries, narrowed to 3.34% on November 9 from 3.42% on November 6. That improvement predates today's inflation release; 3.50% would reverse the improvement, not mark a crisis.
- COUNTERWEIGHT: 68 of 100 sampled stocks are above their 200-day averages; the VIX, expected stock volatility, is about 21, around the 85th percentile over one year. Breadth remains fairly broad, but volatility is elevated.
- INTERPRETATION: A new spread above 3.50% alongside breadth below 55 of 100 would show rate pressure reaching balance sheets, not just stock valuations.
- CONFIDENCE: MEDIUM: Credit predates the inflation release. The contract's 95% hike pricing is an observed market probability, not an observed historical frequency.
🧭 SCENARIO MAP AND WATCHLIST | 5 TO 15 TRADING DAYS
- Base, 45%: Credit stays at or below 3.50%, breadth above 65 of 100; recovery becomes selective.
- Downside, 40%: Credit exceeds 3.50%, breadth falls below 55; financing stress spreads.
- Relief, 15%: Hike odds retreat and VIX falls below 18; the rate constraint eases. These are judgmental weights, not backtested frequencies.
Watch: The next dated credit spread and breadth. Hike odds below 60% would weaken the thesis.
Get the full Sentinel briefing
⚠️ Independent market research for educational purposes only. Not investment advice.