📌 The One Thing That Matters Today
The index looks calmer than the rotation underneath it. After the Fed pause, technology fell while smaller US companies rose. The new information is where support is disappearing.
- Nasdaq 100 🔻 1.55%, Russell 2000 🔺 1.09%: pressure is concentrated in large technology shares.
- S&P 500 🔻 0.46%, VIX 🔻 16.2: a quiet index can conceal a sharp split.
Narrative chart block
Tech Vs Smallcap
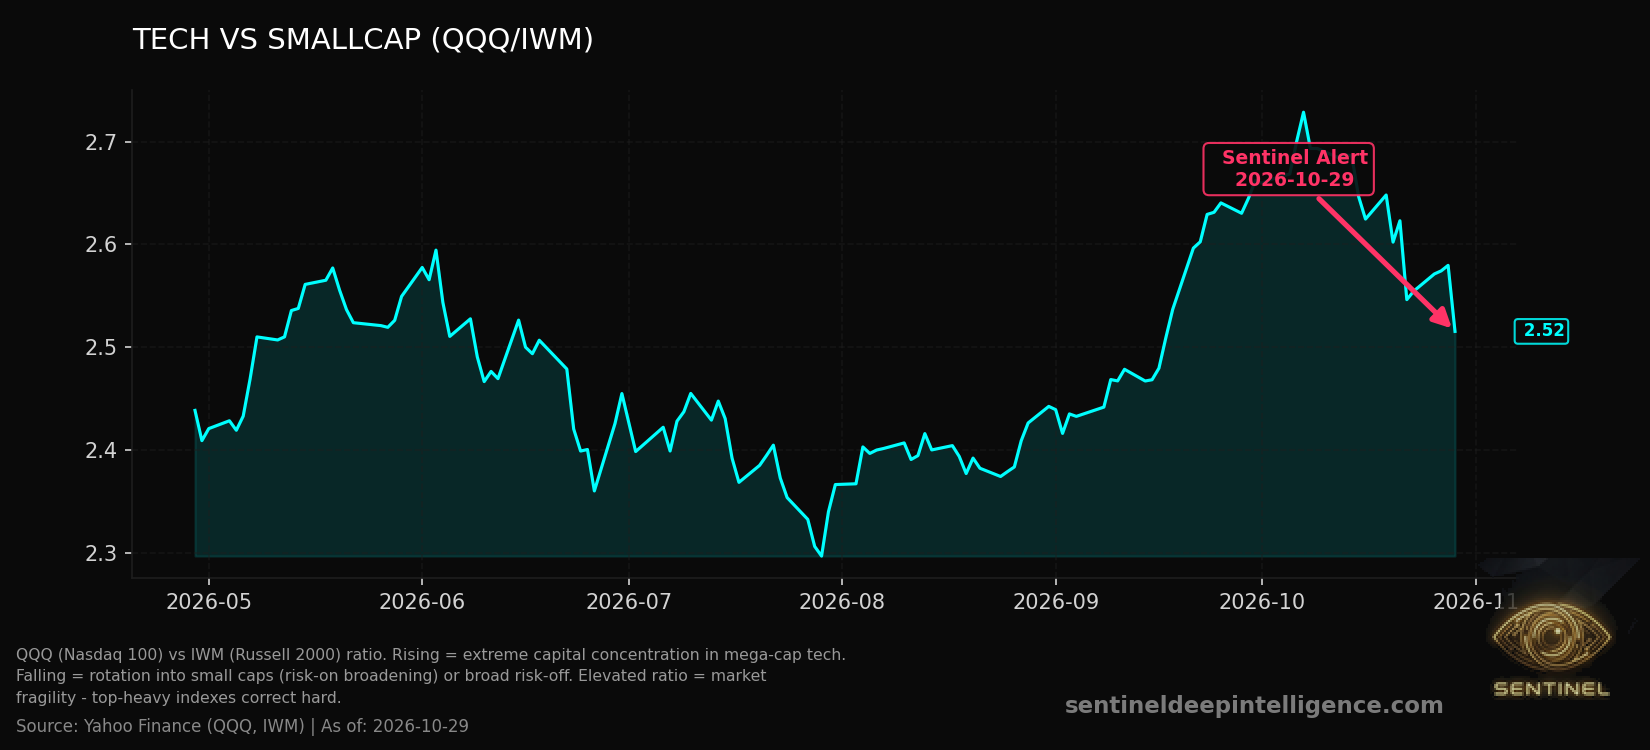
QQQ (Nasdaq 100) vs IWM (Russell 2000) ratio. Rising = extreme capital concentration in mega-cap tech. Falling = rotation into small caps (risk-on broadening) or broad risk-off. Elevated ratio = market fragility —…
📉 ACTIVE LENS: THE INDEX SHOCK ABSORBER
- SIGNAL: An orderly index is rotating beneath the surface. Index calm is not portfolio calm.
- FACT: Estimated positive dealer gamma, options exposure that can damp index swings, was 🔺 $5.6 billion on October 28, from $5.5 billion. It cannot prevent sector repricing.
- INTERPRETATION: Crude near $102 keeps the cost-of-money question alive; a December quarter-point Fed increase trades at 76% in a prediction-market contract. Higher financing costs can weigh on expensive future earnings despite an index shock absorber. Contract odds are not Fed guidance.
- CONFIDENCE: MEDIUM. Gamma can change rapidly. The extra yield on lower-rated corporate debt fell 🔻 to 314 basis points on October 28 from 330 on October 26, arguing against a funding break; 500 is the severe-stress reference. No verified historical hit rate exists for this exact mix.
🔎 SCENARIOS, WATCHLIST AND SIGN-OFF | 5 TO 15 TRADING DAYS
- Base, 50%: rotation persists but borrowing premiums stay below 340; the index remains more stable than its weakest sector.
- Downside, 30%: oil holds above $100, borrowing premiums rise past 340, and participation weakens; sector pressure spreads into financing.
- Relief, 20%: oil slips below $100 and technology catches up while borrowing premiums remain contained.
- Watch: the technology-to-small-company ratio, the next dated credit spread, and crude. A sustained technology recovery alongside contained credit would challenge the rotation thesis.
Verdict: rotation, not verified contagion. Scenario weights are subjective judgments, not measured historical hit rates.
Explore the full Sentinel briefing
⚠️ Educational market research only. Not investment advice.