📌 The One Thing That Matters Today
Credit is retreating from last week's equity scare. Lower borrowing premiums challenge the idea that the technology selloff is spreading through corporate finance. Not an all-clear.
- High-yield spread 🔻 330 basis points on October 26, from 340 on October 22: weaker borrowers face a smaller premium over government debt.
- Sampled breadth 🔺 63 of 100 stocks above their 200-day trend, from 59: participation is healing.
- VIX 🔻 17.7, near its 60th percentile over 52 weeks: volatility is not at panic levels; stock fear-and-greed remains 32/100.
Narrative chart block
Hy Spread
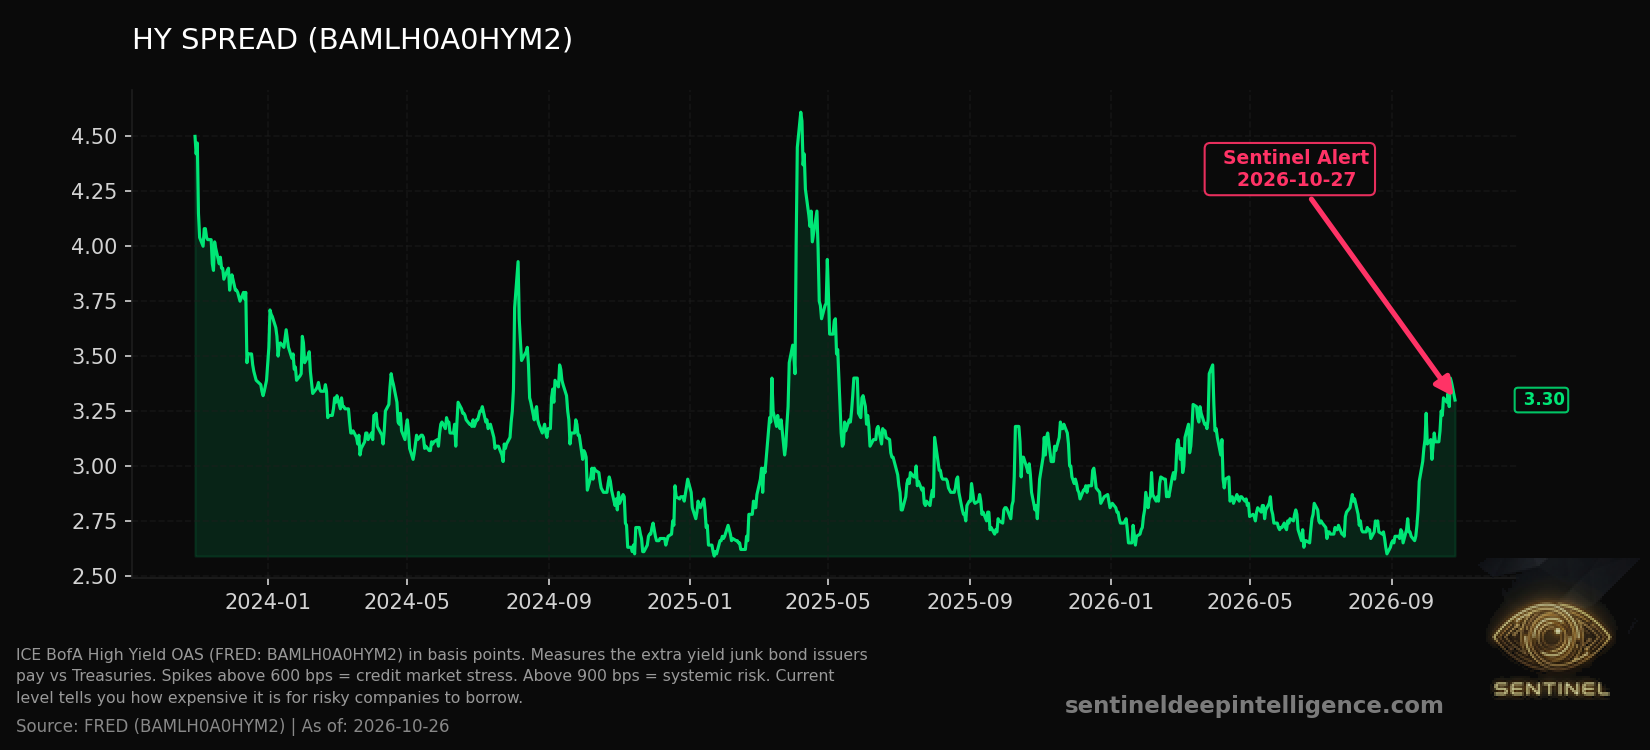
ICE BofA High Yield OAS (FRED: BAMLH0A0HYM2) in basis points. Measures the extra yield junk bond issuers pay vs Treasuries. Spikes above 600 bps = credit market stress. Above 900 bps = systemic risk. Current level…
📉 Active Lens: The Credit Cross-Check
- SIGNAL: Lenders have eased their risk premium twice since October 22; this is more than one reassuring print.
- FACT: Monthly high-yield widening is now 🔻 37 basis points, below the playbook's 50-point divergence threshold; no fresh equity high is verified. The spread also remains far below the 500-point severe-stress marker.
- INTERPRETATION: If credit eases while more stocks stay above their 200-day average, a sector selloff is less likely to become a financing shock. Positive dealer gamma near $4.3 billion may soften index swings, not repair bad loans.
- CONFIDENCE: MEDIUM. Credit is dated October 26; today's equity readings are newer. Earnings could reverse the narrowing.
- FREQUENCY CHECK: The full historical divergence setup is absent. Its past outcomes are not a valid hit rate for today's partial configuration.
🔎 SCENARIOS AND WATCHLIST | 5 TO 15 TRADING DAYS
- Base, 55%: credit stays at or below 330 and breadth above 60/100; the correction remains uneven.
- Downside, 25%: credit returns above 340 with breadth below 50/100; broader repricing becomes more credible.
- Relief, 20%: credit approaches 327 while breadth holds above 60/100; the October jump looks temporary.
- Next test: credit and breadth must move together. A firm index on its own cannot settle the question.
Verdict: contagion risk has eased, not vanished. These weights are subjective scenario judgments, not measured historical frequencies.
Explore the full Sentinel briefing
⚠️ Educational market research only. Not investment advice.