📌 The One Thing That Matters Today
A falling index does not mean credit is breaking today. US stocks reversed Thursday, while riskier companies' borrowing premium narrowed Wednesday. The signals cover different sessions.
- S&P 500 🔻 1.0% near 7,677 Thursday: the rebound has lost ground, not reached capitulation.
- VIX 🔺 near 18, around the 67th percentile of its past-year range: concern has risen, below the year's high near 31.
- 59 of 100 tracked stocks remained above their 200-day averages: most hold their trend, though this is a sample.
Narrative chart block
Hy Spread
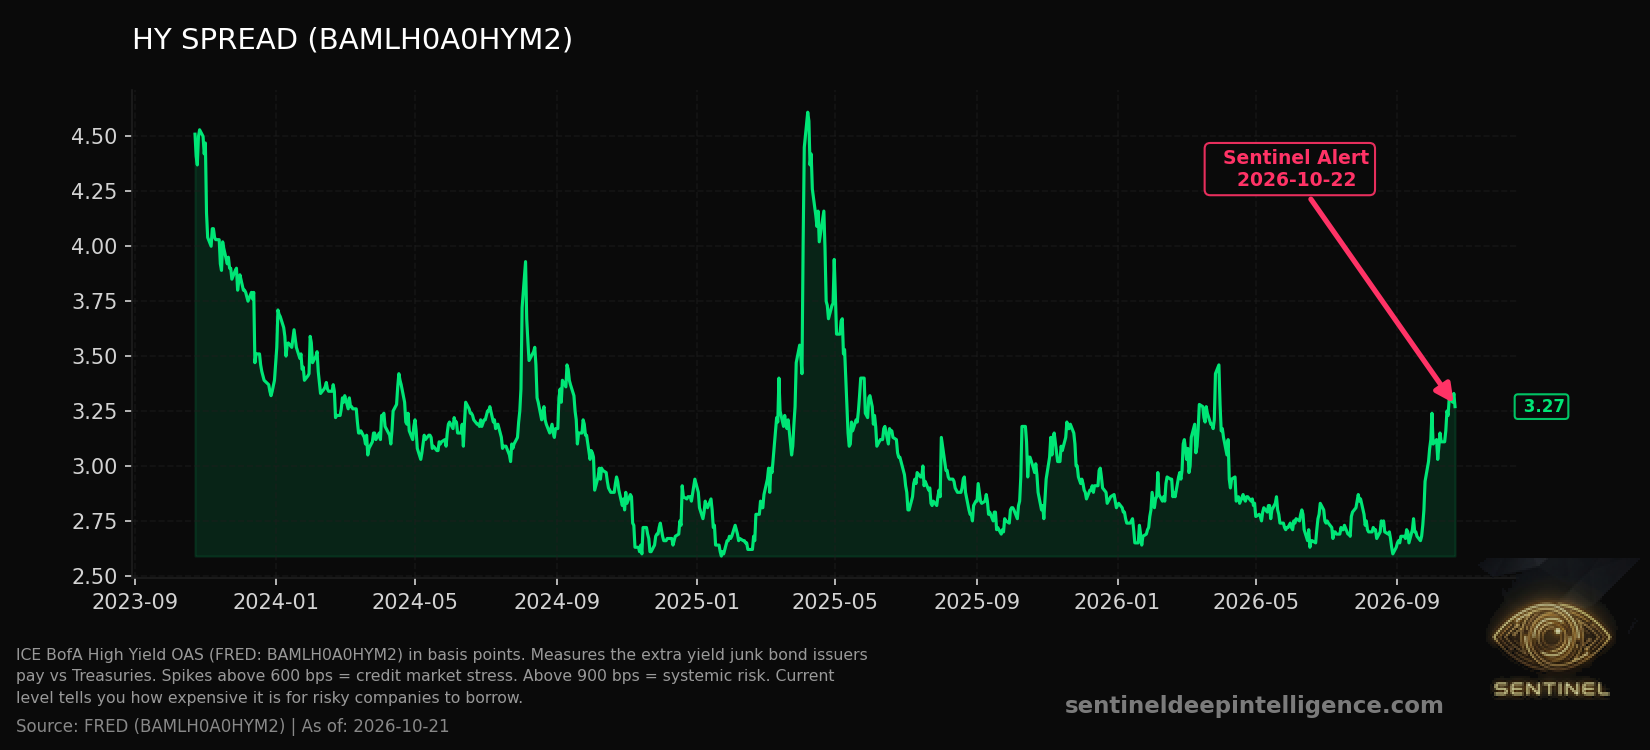
ICE BofA High Yield OAS (FRED: BAMLH0A0HYM2) in basis points. Measures the extra yield junk bond issuers pay vs Treasuries. Spikes above 600 bps = credit market stress. Above 900 bps = systemic risk. Current level…
📉 Active Lens: The Credit Cross-Check
- SIGNAL: Falling shares and slightly cheaper credit are not yet a synchronized financing shock.
- FACT: The US high-yield spread, the extra interest weaker companies pay above government debt, fell 🔻 to 327 basis points on October 21 from 333. One basis point is 0.01 percentage point. Over 30 days it remains 🔺 59 points wider, beyond a 50-point warning scale but below the 500-point severe-stress marker.
- INTERPRETATION: One day's cheaper debt challenges accelerating stress, but not a month of costlier borrowing. Wednesday's +$6 billion estimated dealer options buffer could soften swings, not refinance companies. A seatbelt is not a new engine.
- CONFIDENCE: MEDIUM. Credit and options readings precede Thursday's decline. Narrowing spreads with broader participation weaken caution; widening with thinner participation strengthens it.
- HISTORICAL FREQUENCY: 3 of 3 selected credit-divergence episodes in 1998, 2007 and 2020 preceded equity declines. Those were not comparable observations of today's incomplete setup; 3/3 is not a forecast probability.
🔎 The Next Check
Over 5 to 15 trading days, narrowing borrowing premiums with breadth above half would support repair; widening alongside thinner participation would favor broader repricing. One session establishes neither.
Explore the full Sentinel briefing
⚠️ Educational market research only. Not investment advice.