📌 1. The One Thing That Matters Today
The market is past yesterday's Fed hike. The new issue is restraint: prediction markets price a restrictive Fed through 2026 while oil sits near the inflation line.
- Zero 2026 cuts: 95% 🔺 on roughly $53M of volume. That reprices the whole funding backdrop, not one meeting.
- Crude: $101 🔻 after easing, but above the $90 zone where energy starts influencing inflation expectations.
- VIX: 15.7 🔻 versus the 20 stress line. The surface is calm because hedges are still doing the work.
Oil Price
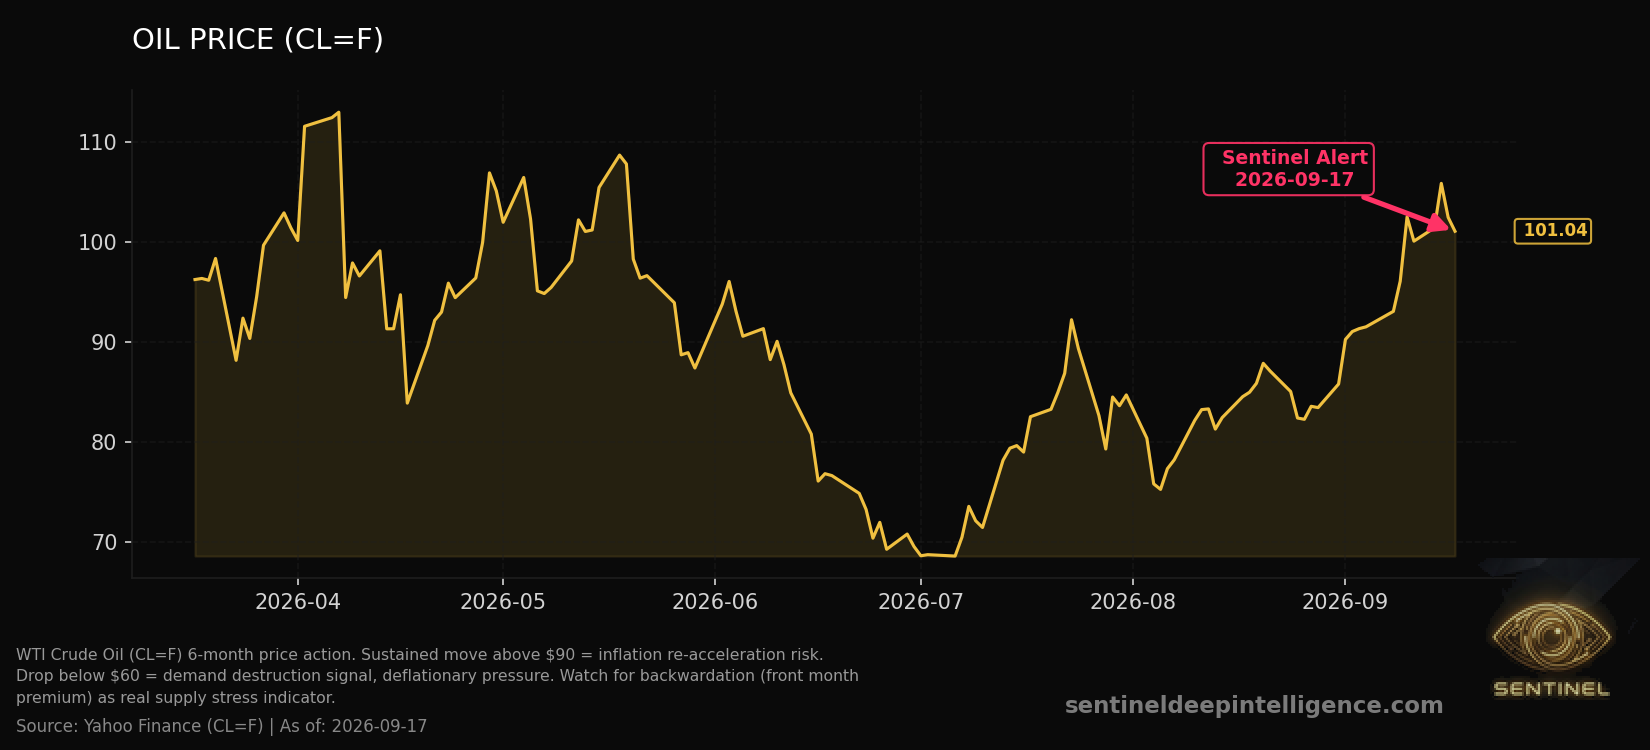
WTI Crude Oil (CL=F) 6-month price action. Sustained move above $90 = inflation re-acceleration risk. Drop below $60 = demand destruction signal, deflationary pressure. Watch for backwardation (front month premium) as…
Spy Vix
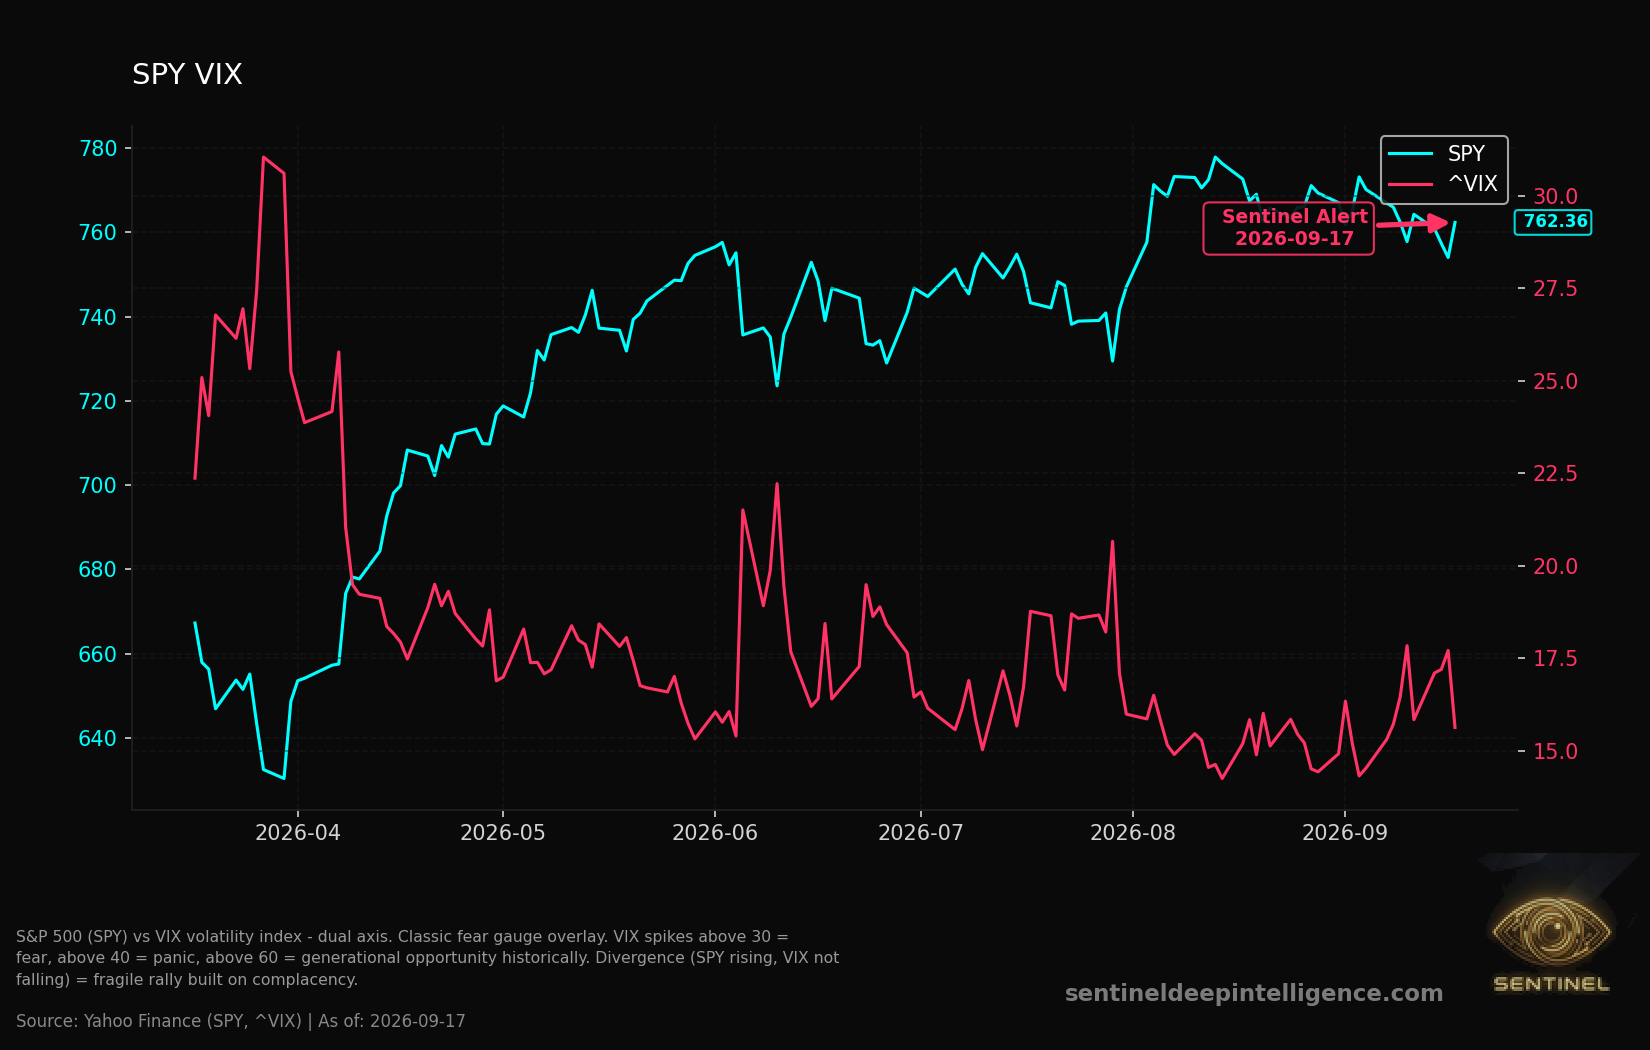
S&P 500 (SPY) vs VIX volatility index — dual axis. Classic fear gauge overlay. VIX spikes above 30 = fear, above 40 = panic, above 60 = generational opportunity historically. Divergence (SPY rising, VIX not falling) =…
📉 2. ACTIVE LENS: POLICY PRESSURE, NOT LIQUIDATION
- SIGNAL: Prediction markets, where real money prices event odds, now treat easier policy in 2026 as unlikely.
- FACT: October is almost even: 52% no change versus 46% for another hike. December still shows a 68% hike probability.
- INTERPRETATION: The public argument is political pressure on the Fed. Capital is pricing inflation credibility. Equities can tolerate a hawkish Fed if oil cools, or expensive oil if the Fed softens. Today they face both.
- CONFIDENCE: HIGH for policy, because volume is current and tied to the Fed event. MEDIUM for equities, because options plumbing can delay repricing.
- In prior playbook cases where rate volatility led equity volatility and VIX stayed below 20, stress moved through yields first. The 5 to 15 day risk is compression, not immediate capitulation.
🧭 3. SCENARIO MAP: 5 TO 15 TRADING DAYS
- Base Case: 45% - VIX stays below 20, S&P 500 holds 7,500, and policy risk mainly lowers tolerance for bad inflation data.
- Downside: 35% - Oil reclaims $105, December hike odds stay above 65%, and S&P 500 loses 7,500.
- Relief: 20% - Crude breaks below $100 and October plus December hike pricing fade together.
👁️ 4. Watchlist
- Crude $105 - inflation pressure becomes active.
- VIX 20 - controlled stress starts reaching equity portfolios.
- December hike odds below 50% - restrictive-policy thesis weakens.
🔓 5. Unlock Full Briefing
Get the complete picture with dark pool data, GEX maps, and all active lenses.
Get the full Sentinel briefing
⚠️ 6. Legal Disclaimer
Research only. Readers decide.